Buying a house is a major financial milestone, but saving enough money to make it happen can feel overwhelming. Between monthly bills, groceries, rent, and other everyday expenses, finding extra money for a down payment isn’t always easy.
The good news is that you don’t need to save a huge amount overnight. With a realistic plan, consistent saving habits, and a few smart financial decisions, you can gradually build the money needed to purchase your dream home.
Whether you’re planning to buy your first house or simply want to become financially prepared for homeownership, this step-by-step guide will show you how to save for a house without putting unnecessary pressure on your budget.
Step 1: Set a Realistic Home-Buying Goal
Before you start saving, decide what kind of house you want to buy and how much it might cost.
Research property prices in your preferred locations. Consider the size, number of bedrooms, neighborhood, and other features that matter to you.
Once you have an estimated house price, calculate how much money you’ll need for the down payment.
For example, if your target property costs $200,000 and you plan to make a 10% down payment, you’ll need $20,000.
Remember that the down payment isn’t your only expense. You should also account for closing costs, property inspections, moving expenses, insurance, and possible repairs.
Having a clear financial target makes it easier to create a savings plan and track your progress.
Step 2: Calculate Your Monthly Savings Target
After setting your home-buying goal, work backward to determine how much you need to save every month.
Your savings target will depend on how much money you need and when you want to purchase your house.
For example, if your down payment goal is $20,000 and you want to reach it within four years, you’ll need to save approximately $417 per month, excluding interest.
If that amount feels too high, consider extending your timeline or looking for ways to increase your income.
The important thing is to choose a monthly savings target that fits your financial situation.
A realistic plan that you can follow consistently is much better than an aggressive target that becomes difficult to maintain.
Step 3: Create a Monthly Budget
A budget helps you understand where your money goes and how much you can put toward your future home.
Start by listing your monthly income and regular expenses, including:
- Rent and utility bills.
- Groceries and household supplies.
- Transportation costs.
- Debt payments.
- Insurance and healthcare.
- Entertainment and personal spending.
Once you’ve listed everything, look for expenses you can reduce.
You might discover that unused subscriptions, frequent restaurant visits, or unnecessary online purchases are taking more money than expected.
Set aside a specific amount for your house savings before spending on non-essential items.
This approach helps you stay organized and makes saving a regular part of your financial routine.
Step 4: Open a Separate House Savings Account
Keeping your home savings separate from your everyday spending money can make it easier to reach your goal.
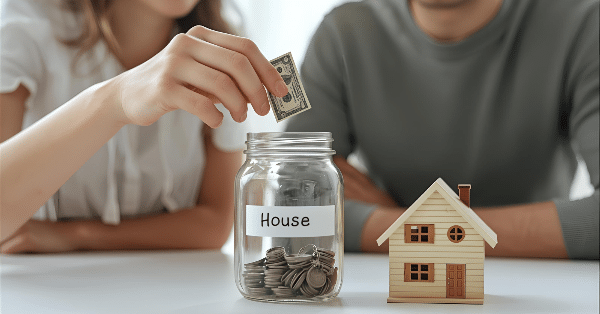
Consider opening a dedicated savings account specifically for your down payment.
Look for an account that offers competitive interest rates, low fees, and convenient access to your money.
A separate account also helps you avoid accidentally spending money you’ve already saved.
For a short-term house-buying goal, prioritize capital preservation and accessibility over high-risk investments.
You want your savings to be available when you’re ready to purchase your property.
Step 5: Automate Your Monthly Savings
One of the simplest ways to stay consistent is to automate your savings.
Set up a recurring transfer from your regular bank account to your house savings account whenever you receive your salary.
For example, you could automatically transfer $250 every month.
This makes saving easier because you don’t have to remember to move the money manually.
It also encourages you to adjust your spending around your savings goal rather than saving only whatever is left at the end of the month.
Whenever your income increases, consider increasing your automatic contribution as well.
Small, consistent deposits can gradually turn into a substantial down payment.
Step 6: Reduce Unnecessary Expenses
If you want to save for a house faster, reviewing your everyday spending is a good place to start.
You don’t need to eliminate everything you enjoy. Instead, focus on expenses that provide little value compared with their cost.
Here are some practical ways to save more money:
- Cook at home instead of ordering takeaway regularly.
- Cancel subscriptions you rarely use.
- Compare prices before buying groceries.
- Limit impulse purchases.
- Choose affordable transportation options.
- Avoid unnecessary shopping.
- Look for discounts on essential purchases.
For example, reducing your spending by $100 per month gives you an additional $1,200 per year for your house fund.
These small adjustments can make a meaningful difference over time.
Step 7: Find Additional Sources of Income
Sometimes reducing expenses isn’t enough, especially if you’re working with a limited income.
In that situation, finding ways to earn extra money can help you reach your savings goal sooner.
Consider freelancing, tutoring, part-time work, selling unused belongings, or offering services based on your skills.
You could also explore opportunities to earn additional income through a small side business.
Try putting most of your extra earnings directly into your house savings account.
Even an additional $150 per month could contribute $1,800 toward your down payment over a year.
Choose opportunities that fit your schedule and don’t negatively affect your main job or personal responsibilities.
Step 8: Pay Off High-Interest Debt
High-interest debt can slow down your progress toward homeownership.
Credit card balances and expensive personal loans can consume money that could otherwise go toward your house savings.
Start by reviewing your debts and identifying which ones carry the highest interest rates.
Continue making required payments on all debts while prioritizing expensive balances.
Reducing high-interest debt can free up more monthly income and improve your financial position when applying for a mortgage.
However, don’t use all your available savings to repay debt. Keep enough money for essential expenses and emergencies.
Step 9: Build an Emergency Fund
Saving for a house is important, but you should also prepare for unexpected financial situations.
An emergency fund can help cover medical bills, temporary unemployment, urgent repairs, or other unexpected expenses.
A common recommendation is to save three to six months of essential living expenses, depending on your circumstances.
Keep this money separate from your down payment savings.
Without an emergency fund, an unexpected expense could force you to withdraw money from your house savings and delay your plans.
Financial security makes the home-buying process much less stressful.
Step 10: Track Your Progress and Stay Motivated
Saving for a house is a long-term process, so it’s important to monitor your progress.
Check your savings balance every month and compare it with your original target.
You can use a spreadsheet, budgeting app, or simple savings tracker to see how much you’ve accumulated.
Break your goal into smaller milestones. For example, if your target is $20,000, celebrate reaching $5,000, $10,000, and $15,000.
If your income or expenses change, adjust your savings plan accordingly.
Don’t become discouraged if progress is slower than expected. Consistency matters more than perfection.
Final Thoughts
Learning how to save for a house becomes much easier when you have a clear plan and realistic financial goals.
Start by researching property prices, calculating your down payment, and creating a monthly budget. Then open a separate savings account, automate your contributions, reduce unnecessary expenses, and look for opportunities to increase your income.
Remember to manage high-interest debt and maintain an emergency fund so that your home-buying journey doesn’t put your financial stability at risk.
You don’t need to make huge sacrifices or save everything at once. Small financial improvements, repeated consistently, can bring you closer to owning your dream home.
The best time to start saving for a house is when you have a plan. Take the first step today, stay patient, and keep moving toward your homeownership goal.